7 min read · Updated: 2026-10-11
This guide helps Indonesian readers choose finance tools with confidence, focusing on practical steps and real-world examples. You’ll learn how to compare budgeting apps, savings accounts, and investment platforms without jargon. The aim is to empower smarter money decisions that fit local realities and global options.
By outlining what to look for, how to test each option, and where to beware traps, the article stays useful from planning a budget to starting a small crypto position. You’ll see concrete criteria, like fees, accessibility, and security, that translate into better everyday money management.
Expect actionable comparisons, simple metrics, and a clear path to try and adapt the best-fit tools for your finances.
- Compare tools by concrete costs and actual use, not promises.
- Test real-world scenarios to see how features perform.
- Protect money with security checklists and diversified choices.
- Plan budgets and investments with a simple, repeatable process.
Basics of choosing financial tools
Identify your goals
Start with what you want to achieve: save for a rainy day, invest for long-term growth, or simplify daily spending. Clarify the time horizon and whether you need frequent access to funds. This clarity guides module choices and fee sensitivity. advocaat in Tilburg
- Set clear savings or investment goals
- Match features to needs, not hype
- Test a platform with a small, controlled amount
Consider your income stability and local cost of living when weighing options. A targeted goal makes it easier to evaluate whether a platform fits your plan.
- Define monthly savings target
- List top investment goals
- Note required features (withdrawals, auto-deposits, notifications)
Evaluate fees and accessibility
Fees drive long-term results more than many features. Compare withdrawal costs, monthly charges, and currency conversions if you plan international use. Accessibility includes mobile app reliability and customer support responsiveness.
Test access by simulating a transfer, a small withdrawal, or a quick investment to see processing times. Look for well-documented fee structures rather than vague promises.
How to compare options effectively
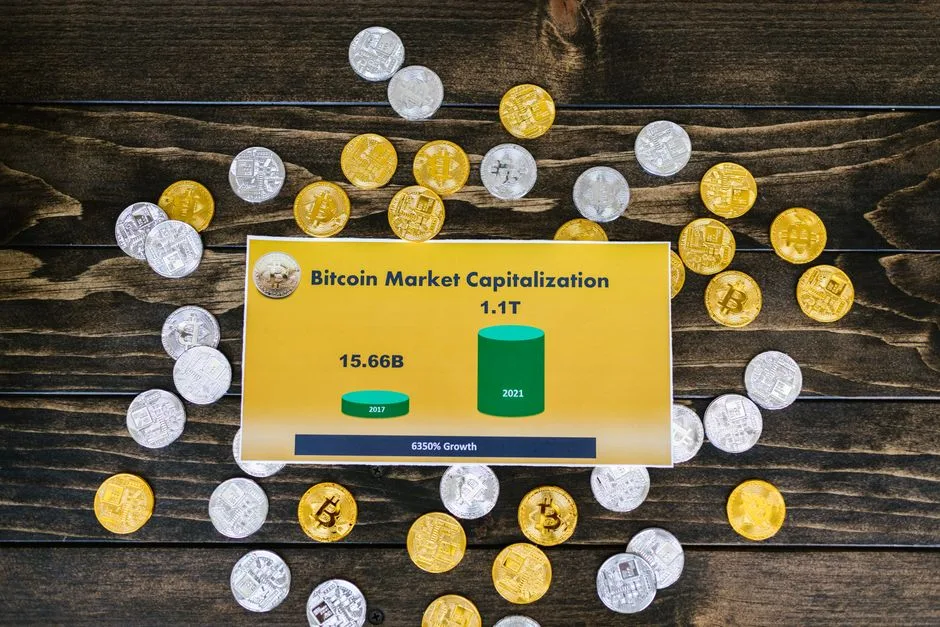
Cost vs value
Create a simple scorecard: weigh fees against features you actually use. For example, a higher annual fee may be justified if it includes advanced budgeting tools, good mobile support, and strong security. Don’t assume value from marketing promises. A useful resource on this topic: wedstrijdnieuws van FC Utrecht.
- Choose by price alone
- Ignore user experience and reliability
- Assume promotions last forever
Use a practical test by running two tools side by side for a month, tracking actual costs and benefits. Document any friction points you encounter.
- Overlooking hidden charges
- Ignoring bundled benefits
- Equating price with quality
Security and control
Security is more than a lock icon. Check two-factor authentication, device limits, and account recovery support. Understand who holds data and how it is used for ads or analytics.
Assess convenience against risk: easier access can mean higher chance of accidental transfers. Look for clear offline backup options and reputable providers with transparent privacy policies.
Practical paths for budgeting and investing
Budgeting tools you can trust
Choose tools that let you set category limits and track progress in real time. A trustworthy budget app should offer category breakdowns, alert thresholds, and exportable statements.
Test data entry with real but small expenses to see how it adapts to spending patterns. Look for automatic syncing with bank accounts and straightforward reconciliation features.
- Link bank accounts securely
- Set weekly review habit
- Export monthly reports
- Adjust categories as needed
| Option | Fees/Access | Value/Limitations |
|---|---|---|
| Budget app A | Moderate charges | Good tracking tools for beginners |
| Brokerage B | Low fees | Strong diversification options |
| Banking C | No monthly fee | Limited investment features |
Investing with a cautious approach
If you are new to investing, start with a simple, diversified approach and a clear risk limit. Use low-cost index funds or broad ETFs where available, and avoid attempting to time markets.
Auto-invest features can steadily grow capital without constant decisions. Keep a small emergency fund separate from investments.
Relying on one wallet, exchange, or bank makes you vulnerable to outages, policy changes, or security issues.
Common financial pitfalls to avoid
Overlooking fees and terms
Even small fees can accumulate over years. Read the terms for withdrawal limits, conversion costs, and inactivity charges. Short-term savings often get eroded by recurring fees.
- Ask for full cost breakdown
- Negotiate where possible
- Prefer transparent pricing
Ask for a fee breakdown and compare it to similar options. If a provider won’t disclose costs, proceed with caution.
- Ignore fee structures
- Assume low-cost equals best
- Overlook long-term impact of charges
Relying on a single platform
Diversify tools to reduce risk. Relying on one wallet, exchange, or bank makes you vulnerable to outages, policy changes, or security issues. Split funds across different providers with differing permissions.
Keep a small, curated set of trusted tools for daily needs and a separate option for longer-term goals.
- Limit exposure per platform
- Maintain separate liquidity pools
- Regularly review provider changes
Tax considerations
Income tax implications for tools
Choose tools with transparent fee structures to avoid hidden charges that reduce net gains. Consider how commissions on investments or rewards on savings affect your after-tax returns. For a self-directed plan, understand how gains are taxed differently from ordinary income in Indonesia.
Compare tax treatment across accounts, such as tax-advantaged savings versus regular brokerage accounts. When possible, use tax-loss harvesting where allowed to offset gains and improve after-tax outcomes.
Be aware of annual tax reporting requirements, calendars, and any forms you must file to stay compliant. Keeping good records helps prevent surprises at year-end and simplifies the process.
- Track fees and compare after-tax outcomes
- Note annual tax deadlines
- Keep receipts for investments and trades
- Review changes in tax policy before year-end
Crypto and fiat interplay
Balancing crypto with local currency
Crypto exposure adds diversification but introduces price swings that affect liquidity. Balance crypto investments with stable, readily accessible fiat to cover regular expenses. This keeps your day-to-day finances resilient during market swings.
- ☐ Define a maximum crypto share in your portfolio and stick to it.
- ☐ Track the cash needed for monthly expenses in fiat.
- ☐ Review how gains and losses are taxed for crypto activities.
Use dollar-cost averaging for crypto purchases to smooth entry points and avoid timing the market. Decide in advance how much of your portfolio you devote to volatile assets.
Keep a clear separation between speculative crypto bets and essential funds like emergency savings. Do not mix the two.
- Set a crypto allocation that aligns with risk tolerance
- Maintain an accessible fiat cushion
- Define a withdrawal plan during volatility
- Document tax considerations for crypto trades
Regional tools and services
Indonesia-first financial products
Seek tools that are designed for the Indonesian market, with local features like ID-based onboarding and familiar payment rails. These protect you with suitable regulatory coverage and compatible interfaces for daily use.
Compare regional banks, fintechs, and investment platforms on ease of deposit, withdrawal, and customer support responsiveness. A good partner should explain fees in clear terms and offer local language help.
Evaluate mobile apps for reliability, security features, and offline access during outages to avoid missed payments or data gaps.
- Look for local support and language options
- Check fee clarity and transfer speeds
- Assess app stability and security features
- Verify regulatory registration and protections
Final checklist for readers
Putting it into practice
Create a simple budget that covers essentials, savings, and debt repayment before allocating any funds to investments. This baseline helps you avoid overexposure to risky assets.
List the tools you will use for six months, including fees, minimum balances, and withdrawal rules. Review regularly to catch drifts in costs or features.
Set a monthly review date to adjust your plan as life changes, like a job change or a new family member. This keeps your strategy aligned with goals.
Incorporate safety nets such as an emergency fund and a plan for debt consolidation if needed.
- Draft a basic budget in one page
- Track fees and minimum balances
- Schedule regular plan reviews
- Maintain an emergency fund
Frequently asked questions
Are Indonesian tools subject to the same tax rules as foreign platforms?
Most gains from Indonesian instruments fall under local tax regimes, and foreign platforms may have different reporting obligations. Verify how each tool reports income to you and to the tax authority, and how withholding is handled. This helps prevent surprises at year end.
Can crypto be part of a long-term savings plan in Indonesia?
Crypto can be a small, diversified addition to a broader portfolio, but it should not replace core savings. Maintain a fiat buffer for daily needs, and limit crypto exposure to a level you can tolerate during price swings.
What should I look for in regional banking apps?
Prioritize clear fee structures, reliable transfers, and strong security features like biometric login and transaction alerts. Also test customer support responsiveness and the availability of local payment rails.
How often should I review my financial toolkit?
Set a quarterly check-in to compare costs, performance, and new features. If you experience a life change, adjust the plan sooner to keep it aligned with your goals.
Conclusion
A practical toolkit comes from balancing certainty with flexibility. Choose tools that fit your Indonesian context, keep costs visible, and maintain discipline with monthly reviews.
Take the next step by drafting a short plan: outline your budget, list your chosen tools, and set a three-month trial to test reliability and ease of use.
For a deeper understanding of this topic, How to approach advocaat in Almere: offers valuable insights worth exploring.
If you enjoyed this article, we recommend checking out Tarayıcı.net için karar rehberi: otomobil odaklı for further reading.
Readers interested in this subject may also want to explore Smart money moves: a practical guide for additional perspectives.